Riverview, New Brunswick
RIVERVIEW BUSINESS
FINANCING.
Riverview runs on companies that answer their own phones — owner-operated contractors, home and commercial services, trades, local retail and food service, professional and small businesses serving the town and the wider metro across the bridge. BizFin.ca helps Riverview businesses explore equipment financing, commercial vehicles, working capital and growth options, with a review that reads a small-business file the way it deserves to be read.
AN OWNER-OPERATED ECONOMY SOUTH OF THE RIVER.
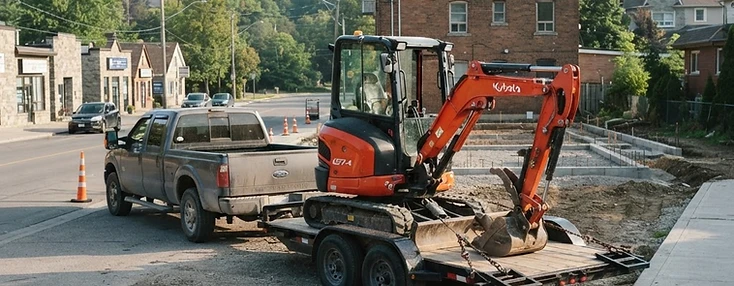
Riverview's business community is not a scaled-down copy of the metro across the water; it is its own market, built on companies whose owners live a few streets from the shop. Contractor crews roll out at dawn, landscaping and property-care routes wind through the neighbourhoods, renovation and trade specialists work homes and commercial buildings on both sides of the river, and restaurants, retailers and professional practices serve a town that has grown steadily for decades. Growth of that kind leaves a paper trail — equipment lists, truck schedules, project calendars — and that is exactly where financing starts.
The financing picture here has two halves that deserve separate treatment. One is assets: contractor packages, landscaping and property-care equipment, service vans and pickups, shop tools, commercial kitchens, and the technology a professional practice runs on. The other is cash: materials bought ahead of a project, crew payroll carried between draws, inventory for a growing local store, the wait between invoicing a commercial client and getting paid. This page covers both, in the order a Riverview owner actually deals with them.
EQUIPMENT FINANCING IN RIVERVIEW.
Contractor packages, landscaping machinery, shop tools, commercial kitchens and refrigeration, practice technology.
COMMERCIAL VEHICLES IN RIVERVIEW.
Contractor pickups, enclosed trailers, service and cargo vans, delivery units — business use only.
WORKING CAPITAL IN RIVERVIEW.
Project materials, crew payroll between draws, inventory, receivable timing, marketing, seasonal dips.
RIVERVIEW BUSINESSES SERVED.
Contractors and trades, home and property services, restaurants and retail, professional and office businesses.
South of the Petitcodiac
A MARKET THAT STANDS ON ITS OWN SIDE OF THE RIVER.
The bridge to the metro is a fact of geography, and plenty of Riverview companies work both sides of it — but the business base here is local first. The town carries its own commercial strips, its own service economy and its own customer base, and owner-operators here tend to serve the neighbourhoods they know: homes, small commercial buildings, local institutions, and the steady renovation and repair work a growing town generates. A financing review reads that correctly — a Riverview file is a Riverview file, with its own premises, its own customer mix and its own calendar, not an appendix to a bigger city's story.
That independence matters commercially, too. Local service businesses win on reputation and responsiveness, not on scale, and the ones that grow do it by adding capability — a second crew, a better machine, a bigger shop — one deliberate step at a time. Financing built for owner-operated companies is designed around exactly those steps: right-sized requests, clear asset stories, cash solutions matched to project rhythms rather than corporate fiscal calendars.
Contractors, trades and home services
THE CREWS THAT KEEP A GROWING TOWN MAINTAINED.
Construction, renovation and the property trades are the backbone of the local business base: general contractors and renovators, the electrical, plumbing and heating specialists a growing housing stock calls constantly, landscaping and property-care companies, and the shops that repair and outfit them all. Their asset list is work-shaped — skid steers and mini-excavators, enclosed trailers, mowers and property-care equipment, ladders and lifts, table saws and shop tooling — and their cash list is project-shaped: materials bought ahead of the job, deposits and draws, crew payroll carried between milestones, the quiet month that follows a busy one.
Equipment financing for this layer usually starts with a package: a quote or an equipment list covering the whole acquisition — machine, trailer, attachments — reviewed as a single file, with delivery and installation travelling along where the program allows. Used equipment with honest service records belongs in the same review at the right price-to-life comparison. The operating side is kept deliberately apart: project timing and payroll are working-capital matters, and treating them as such keeps both files cleaner.
Local commerce and food service
THE RESTAURANTS, RETAILERS AND SERVICES ON THE STRIP.
The town's commercial strips carry a dense layer of owner-run commerce: restaurants and cafés, specialty retail, salons and studios, service businesses that live on walk-in traffic and local word of mouth. Their equipment is the classic commercial set — commercial kitchens, refrigeration and exhaust systems, fixtures and fit-out, point-of-sale and booking technology — and their cash rhythm follows the calendar: inventory bought ahead of the season, staff hired for the rush, receivables timed to how local customers actually pay.
Financing for this layer is sequenced rather than lumped: the kitchen or the fit-out lands ahead of the busy season, working capital carries the stock-and-staff build and the quieter weeks after, and an expansion — a second location, a renovated room, a broader line — opens in front of demand. A review can plan those pieces together instead of forcing a restaurant, a shop or a studio into a generic product.
Professional and office businesses
PRACTICES AND SMALL OFFICES WITH THEIR OWN NEEDS.
Riverview also carries a professional layer that runs quietly alongside the trades: accounting and bookkeeping practices, insurance and financial-services offices, health and wellness practices, design and consulting businesses working from small offices or home-based studios. Their equipment is lighter — workstations, servers and practice technology, client-facing fit-out — but their investment is in people, and people are financed differently: a hiring class brought on ahead of revenue, a marketing push, the gap between delivering a service and collecting for it.
For these businesses the review starts from cash flow rather than machinery. Working capital carries the growth of a practice; a modest technology or fit-out file, where one exists, is kept separate from the operating money it should never be mixed with. The result is a plan that matches how an owner-manager actually grows — deliberately, against real demand.
Equipment and vehicles in Riverview
FROM SKID STEERS TO SERVICE VANS.
The equipment list across the town reads like its economy: contractor and trades packages, landscaping and property-care machinery, shop tools and repair equipment, commercial kitchens and refrigeration, practice and office technology. The vehicle list matches — contractor pickups, enclosed trailers, service and cargo vans for the home-services companies, delivery units for the retailers — and every one of them is business-use financing, structured around what the vehicle does for the company rather than what it looks like in a driveway.
Both lists review well when they arrive with their real shape: a quote or an equipment list for the assets, a route, contract or service book for the vehicles. Used trucks and machines with maintenance records are welcome — late-model service vans and kept-up equipment are the bread and butter of owner-operator files — and complete eligible packages with delivery and installation costs, where the program permits, can be reviewed as one acquisition.
Working capital, growth and succession
THE CASH LAYER — AND THE NEXT OWNER OF THE SHOP.
The working-capital list here is a small-business one: materials and supplier payments ahead of projects, crew payroll between draws, inventory for a growing store, receivable timing when commercial clients pay on their own schedule, marketing that keeps a local name visible, the seasonal dips a service economy rides through. None of it is equipment, all of it is financeable, and keeping the two apart is what keeps both reviews clean.
Growth in a town of owner-operated companies often ends up being a purchase: a contractor buying out a retiring competitor's equipment and customer book, a restaurant family taking over an established local name, a service company adding a second truck and crew. Acquisition and succession files are genuine, reviewable files here — weighed on the business, its cash flow and the program behind the file, with nothing promised in advance.
EXPLORE NEARBY NEW BRUNSWICK COMMUNITIES.
Moncton
Greater Moncton / Southeast
Distribution and logistics hub at the highway-rail junction, with bilingual head-office commercial services.
Business financing in Moncton
Dieppe
Greater Moncton / Southeast
Francophone commercial growth pole at the airport junction — industrial parks and head offices.
Business financing in Dieppe
Shediac
Greater Moncton / Southeast
Acadian coastal tourism and lobster-boat economy by the warm-water beaches.
Business financing in ShediacQUESTIONS ABOUT FINANCING IN RIVERVIEW.
Ready to explore?